INDEPENDENT RESEARCH · SYSTEMATIC TRADING
Researching markets. Building trading systems. Learning from data.
I’m Naman Rathi, a Penn State Finance and Accounting student with an interest in investment research and systematic trading. I build strategies, analyze market data, and develop tools that bring more clarity to financial decisions.

04
Public GitHub repositories
03
Research articles
01
Trading journal application
2027
Expected graduation
Trading Systems
Signal research, backtesting, and rules-based strategy design.
RESEARCH
VN Trading
A journal and portfolio decision workspace linking trades to analysis and reviews.
WEB APPLICATION
Market Perspectives
Short writing on financial markets, investment processes, and risk.
WRITING
FEATURED PROJECT
VN Trading Journal

A connected workspace for better investment decisions
VN Trading brings together trade planning, portfolio records, analysis, and structured reviews. The aim is to understand each decision—not just the profit or loss at the end.
Six connected areas: Home, Trading, Portfolio, Analyze, Review, and Settings.
How an idea becomes a trading decision
01
Research
Identify the market behavior or company question worth investigating.
02
Build
Translate the hypothesis into clear, repeatable rules.
03
Validate
Check assumptions, costs, drawdowns, and benchmark comparisons.
04
Review
Record what happened and refine the investment process.
RESEARCH FOCUS
From a trading idea to a testable process
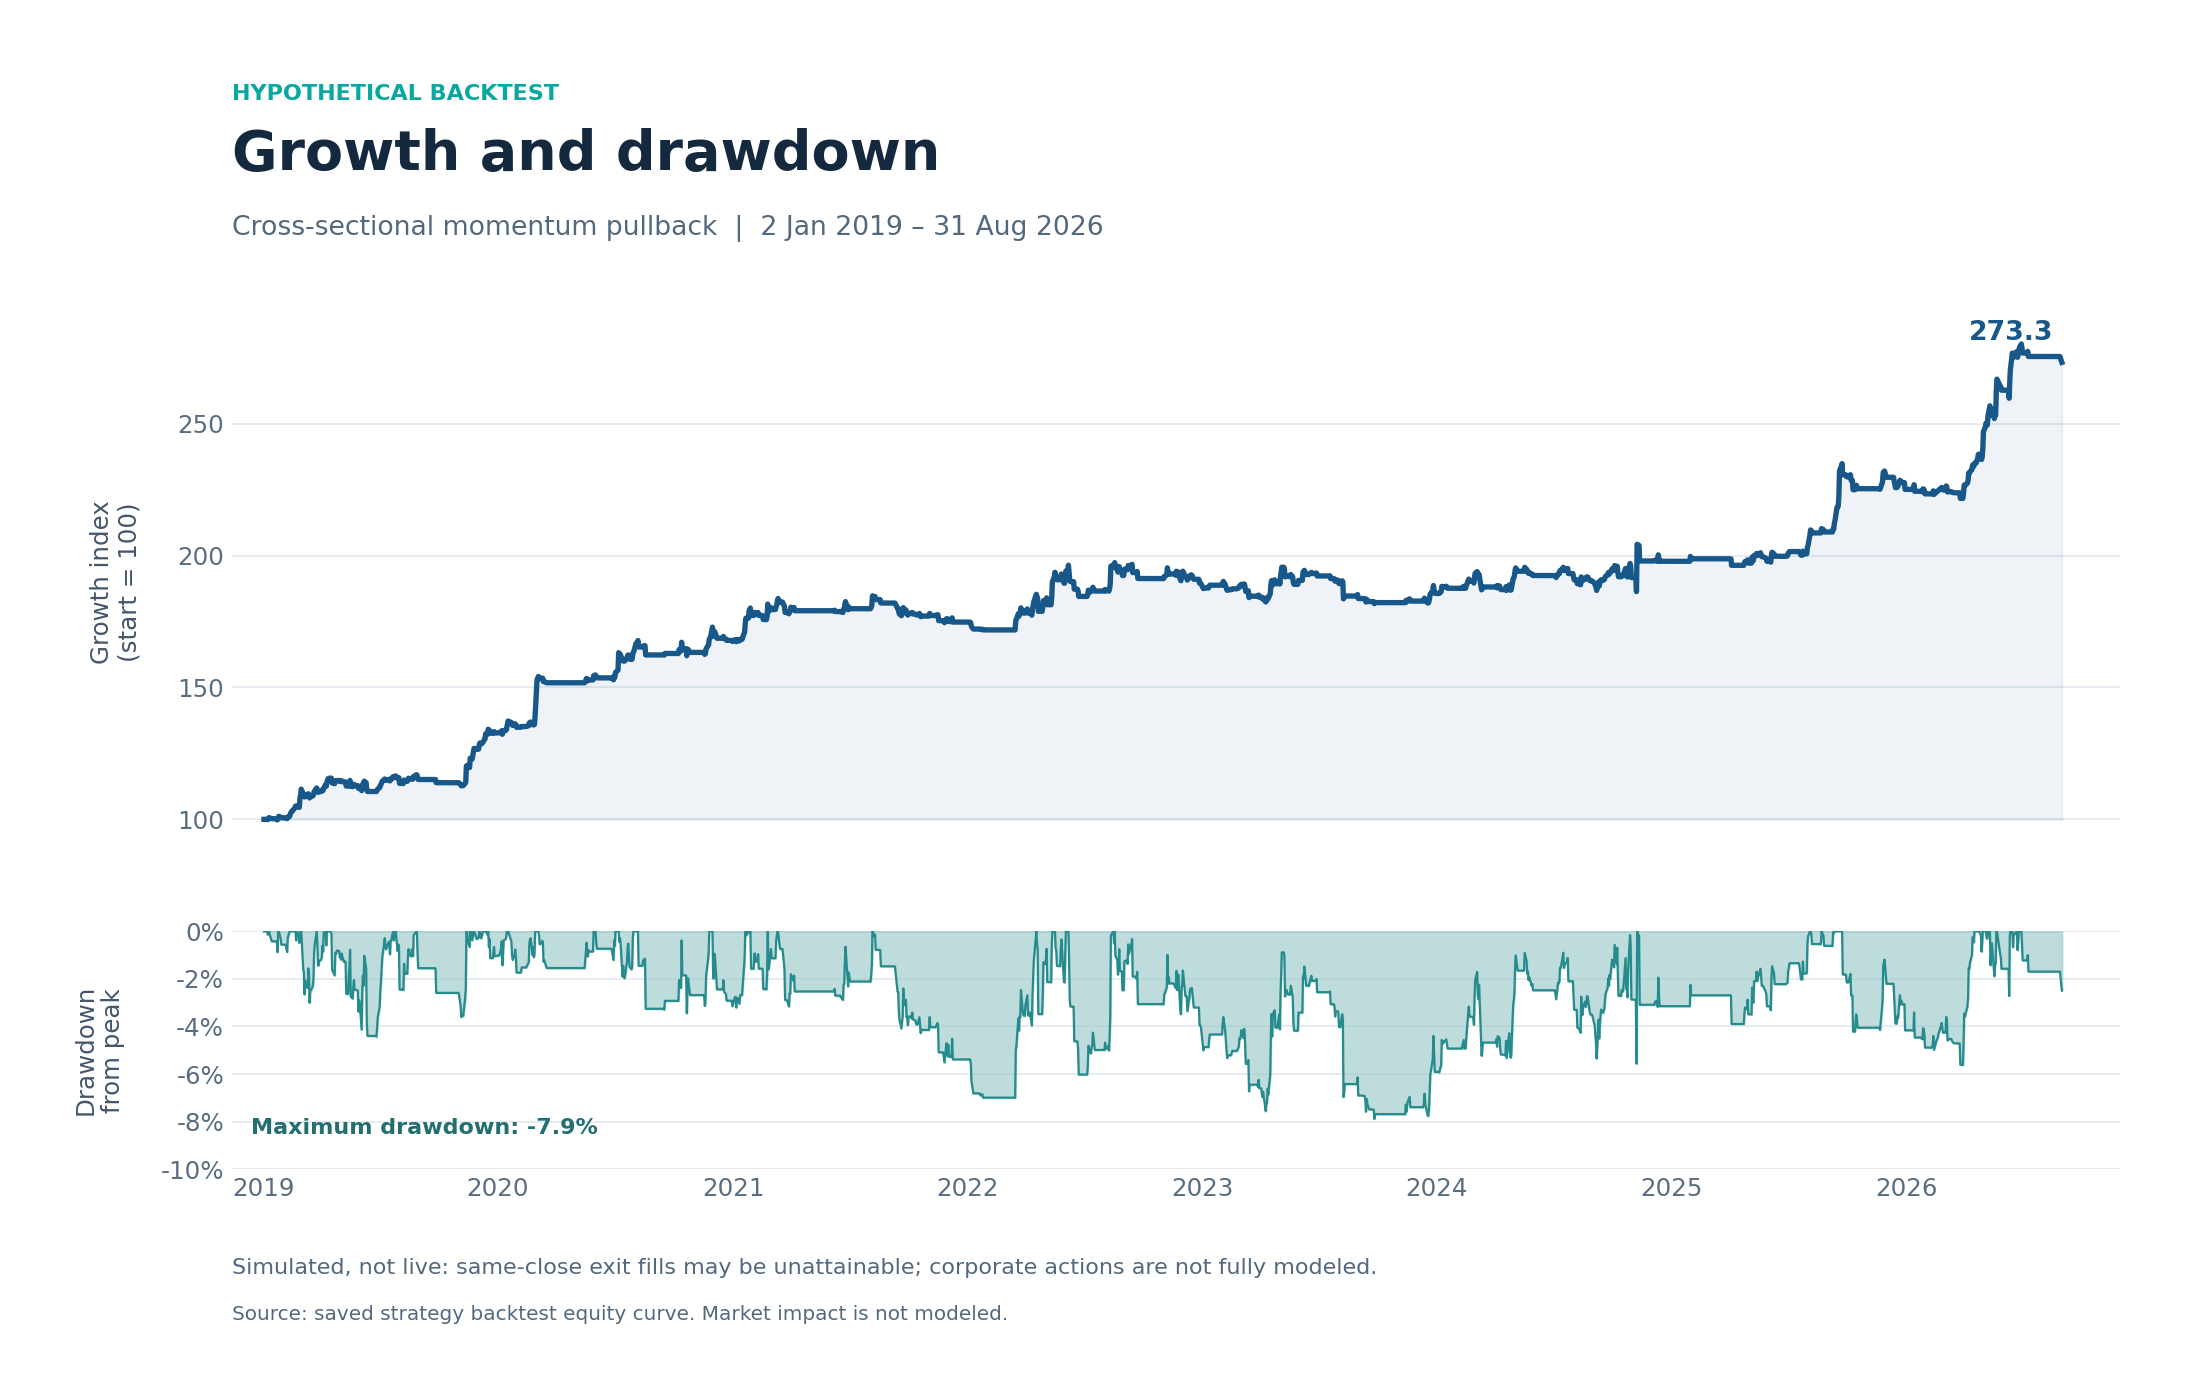
Cross-Sectional Momentum Pullback
The public code release includes Python data and screening pipelines, a portfolio backtester, stochastic research, and synthetic tests. Its preliminary simulated charts include explicit data and execution limitations.
Read flagship research case study → · Explore public code and tests →
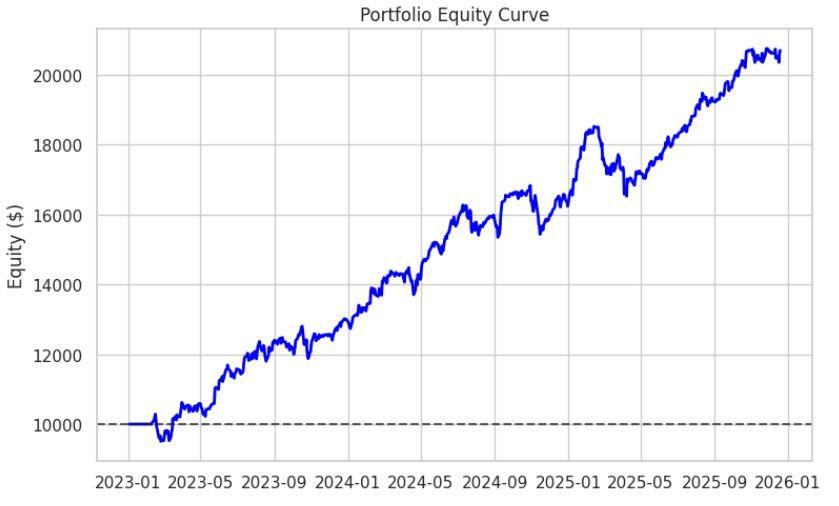
Mean-Reversion Strategy
Z-score mean-reversion research with shared-capital backtesting, explicit risk controls, and original historical portfolio-equity and trade-result visuals.
MORE PROJECTS
Research across markets and tools
AI Portfolio System
Exploratory equity portfolio screening and systematic backtesting.
Coinbase Crypto Momentum
Python modules and synthetic tests cover momentum selection, market regimes, Coinbase connectivity, execution safeguards, and runtime monitoring. The example configuration is observation-only with zero deployment allocation.
LATEST WRITING
Notes on markets, strategy, and risk

What Building a Trading Strategy Taught Me About Risk
Why execution assumptions, overfitting, and out-of-sample testing matter.

AI Infrastructure: Beyond Big Tech
Following capital investment into the broader infrastructure chain.

Returns vs. Investment Risk
Why drawdowns, concentration, and benchmarks belong beside performance.
Interested in the work behind the charts?
Explore my projects or connect with me on LinkedIn for research updates and professional conversations.
