RESEARCH PORTFOLIO
Research & Trading Projects
A collection of systematic strategy research and trading software, including publicly inspectable Python modules, synthetic test suites, methodology notes, and the VN Trading application. Public code is distinct from verified live trading results.
Three areas of work
EQUITIES
Equity Research
Mean reversion, momentum screening, backtesting, and risk analysis.
MARKETS
Systematic Execution
Crypto spot-market regimes, momentum selection, and risk controls.
SOFTWARE
Trading Technology
VN Trading Journal and tools for portfolio decisions and review.
FEATURED APPLICATION
VN Trading — Journal & Portfolio Decision Intelligence
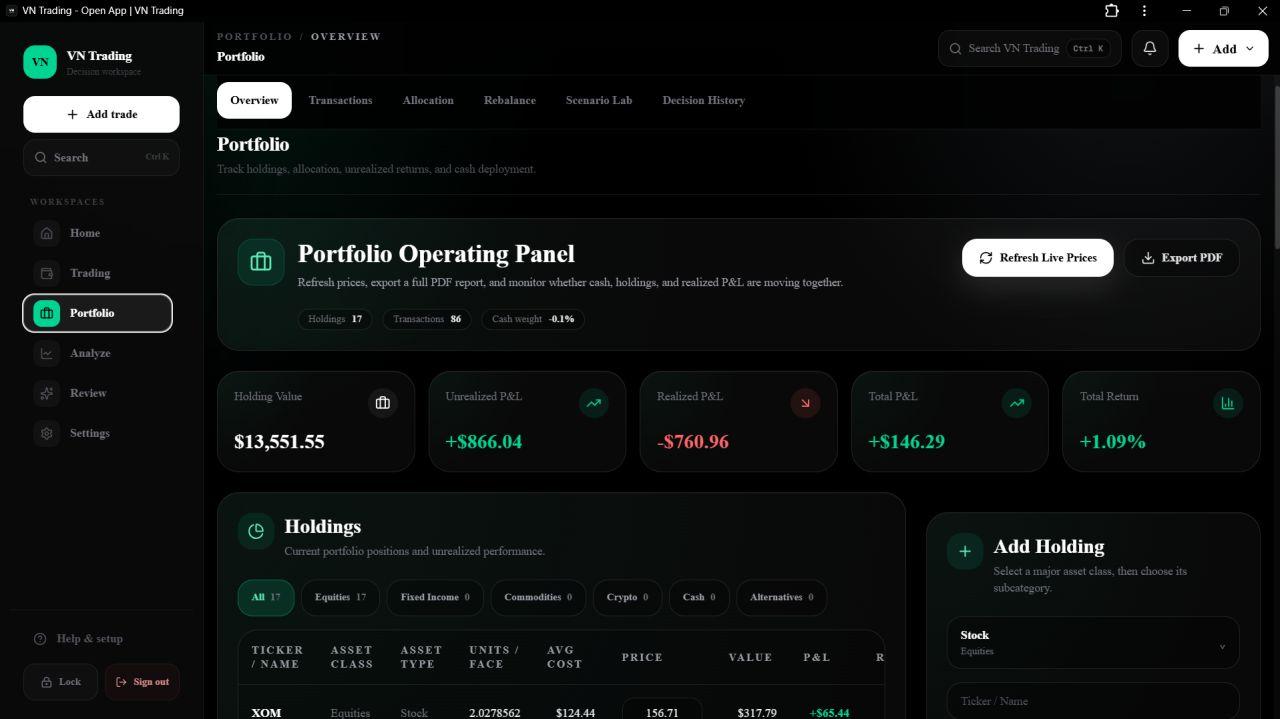
Research, decisions, and reviews in one workspace
VN Trading is a Next.js and Supabase application with six interconnected workspaces: Home, Trading, Portfolio, Analyze, Review, and Settings.
It connects trade planning and import/reconciliation with portfolio accounting, decision evidence, and systematic review. The public application is available to explore.
PUBLIC GITHUB PROJECTS
Quantitative research repositories
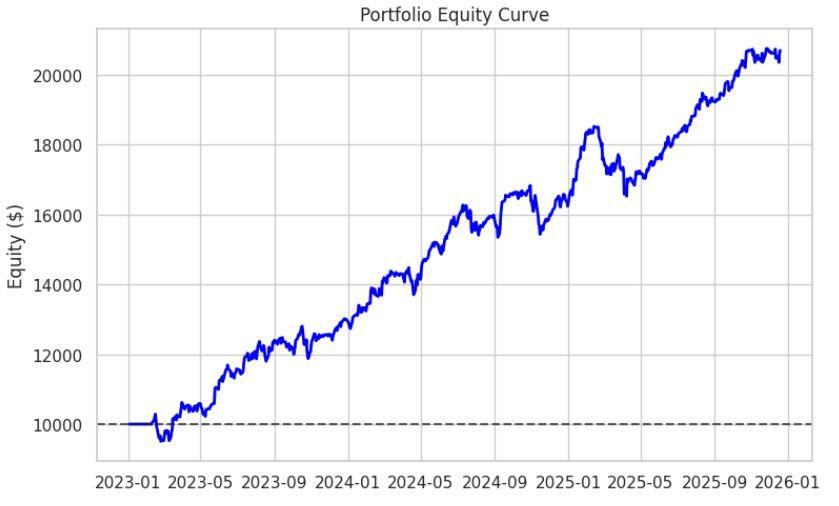
Mean-Reversion Quant Strategy
Python · Public repository
Z-score entry research, mean-reversion signals, index screening, and risk-aware backtesting. The project emphasizes the gap between a theoretical signal and a tradeable portfolio.
See research charts and methodology → · Explore repository →
AI Portfolio System
Screening and backtesting · Public repository
An exploratory portfolio-screening and backtesting project focused on large-cap equities. The public repository currently provides a high-level outline.
MARKET SYSTEMS
Cryptocurrency momentum research
Coinbase Crypto Momentum — Strategy & Execution
Python research, exchange connectivity, and execution engineering
The public Python package covers spot-universe selection, multi-horizon momentum, market-regime logic, Coinbase connectivity, order safeguards, reconciliation, state management, and monitoring. Synthetic tests address strategy behavior, regime transitions, recovery, and operational resilience.
The curated release includes Python source and tests, Windows setup and supervision helpers, and sample configuration. It is an inspectable research implementation, not an audited performance record or validated production deployment.
Inspect strategy and execution modules → · Browse synthetic tests →
Public Source, Tests & Safety Defaults
Curated source release · Python 3.11+ · Synthetic tests
Visitors can inspect src/crypto_momentum/, tests/, requirements.txt, example environment settings, and setup scripts. The public sample defaults to observation mode with zero deployment allocation. Credentials, account history, logs, and runtime state are excluded. Because live-order functionality exists in the source, the example must not be treated as production-ready.
ADDITIONAL RESEARCH
Momentum Research & Risk Diagnostics
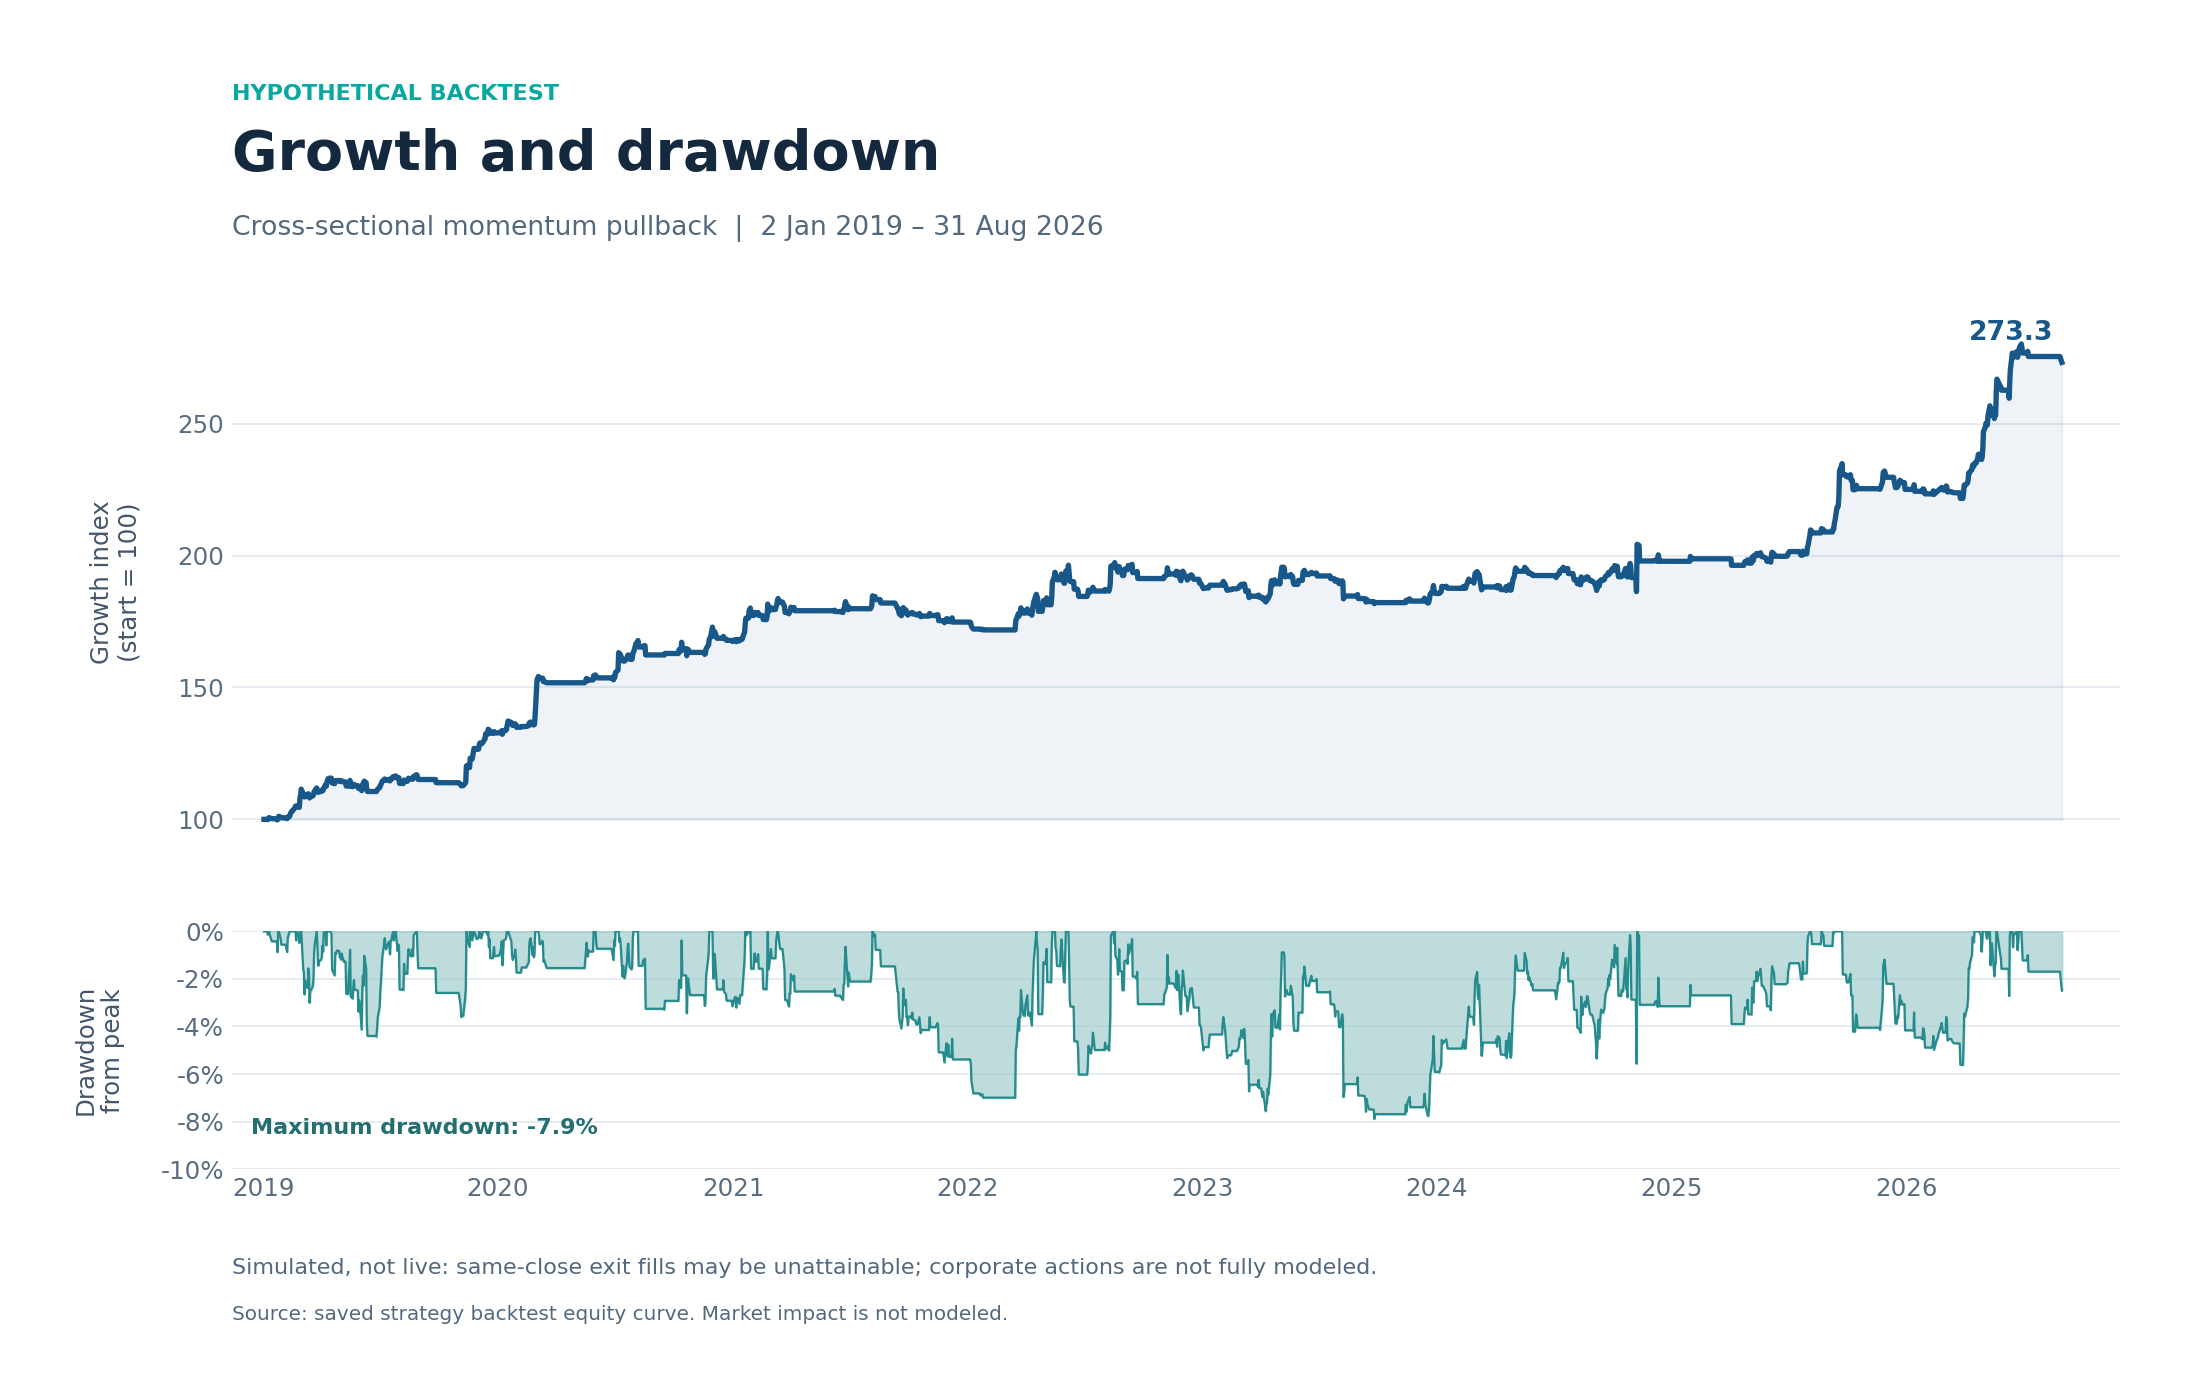
Cross-Sectional Momentum Pullback
A long-only equity research strategy selecting momentum leaders and studying controlled pullbacks. Its curated public release includes Python data normalization, feature engineering, monthly screening, portfolio backtesting, forward-data preparation, production-state checks, stochastic research modules, and synthetic tests. My broader research included a 729-combination parameter study. Preliminary 2019–August 2026 results are simulated, unaudited, and subject to material execution-timing, corporate-action, and benchmark limitations.
Read code, methodology and simulation disclosures → · Inspect core Python modules → · Browse synthetic tests → · Stochastic research →
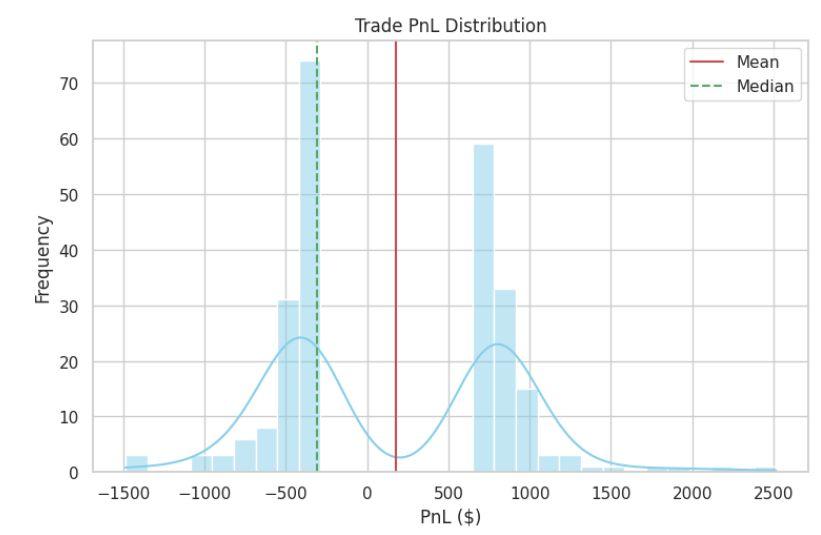
Trade Distribution & Research Validation
Original Z-score mean-reversion trade P&L diagnostics demonstrate how average profitability, losses, dispersion, and the shape of outcomes matter beyond a portfolio equity curve. The case study explains the risk and execution assumptions behind the simulation.
GITHUB INDEX
Repository links at a glance
Public Application
VN Trading — a trading journal, portfolio analytics, and decision-review application. Explore the live application →
Four public GitHub repositories are linked here. The two momentum overview repositories now contain curated Python source, sample configuration, and synthetic tests—not just project summaries.
Explore the source, then the thinking.
The public GitHub repositories include source code, synthetic tests, architecture notes, and documented research limitations. The work is inspectable, but simulated results are not independently audited, and the published notices reserve reuse and redistribution rights. For professional updates, connect on LinkedIn.
